
You're buying again, and an AI price estimate looks like a quick way to settle on an offer. But does it account for the home's condition, and are those nearby sales actually good comparisons? An ai realtor tool is useful when you can question its evidence. Use it to prepare your pricing and paperwork questions, while your licensed broker handles the binding offer with your approval.
TLDR:
Use AI realtor tools for your next purchase, but leave binding offers to a licensed broker.
Check your price estimate against 3 to 6 nearby comparable sales from the past 3 to 6 months.
Ask AI to flag disclosure and inspection conflicts, with page references you can verify.
Get your verified pre-approval from a lender. AI budget estimates cannot replace it.
Homa pairs AI home analysis with licensed representation for your purchase in Florida or Texas.
What "AI Realtor" Actually Means
“AI realtor” is shorthand for tech that helps you buy a home, not a real estate license or professional designation. If you’re buying again, these tools can help you check asking prices and review disclosures before you discuss findings with your broker. Examples include a search assistant that turns your wish list into property matches, an automated home-value estimator, or a document tool that flags conflicting roof details in your disclosures and inspection report.
Some tools turn your preferences into listing results. Others help you compare prices or review property documents. Some offer guidance alongside licensed professionals, who handle representation and transaction work, part of a broader shift toward AI-powered home buying.
When comparing AI realtor services, check what the software does, what requires a licensed professional, and who is responsible for your transaction.
How Buyers Are Already Using AI in Their Home Search
AI realtor tools can help with familiar homebuying tasks, but buyer interest is not proof of completed AI-only purchases. In a June 2026 Veterans United Home Loans survey, 53% of prospective homebuyers were comfortable buying without direct human involvement; 68% trusted AI-based mortgage information.
For your next purchase, practical uses include:
Comparing your previous lender with other options before you make calls.
Comparing loan options against how long you plan to own.
Organizing your paperwork as it arrives.
Start with a task that took too much time during your last purchase.
AI for Home Search and Discovery
Traditional MLS filters use fixed criteria, such as price and bedroom count. AI realtor search tools can let you describe your next home in plain English, with feeds that adapt as you browse.
Use what you learned from your last purchase: “I need desk space outside the bedrooms and less yard maintenance.” Keep your budget ceiling firm.
Tools that learn your preferences can suggest homes beyond your original filters, including listings with unexpected wording for usable space. Check suggestions against listing details: a breakfast nook may still make a poor office.
AI for Home Valuation and Pricing
For your next purchase, AI pricing tools can check asking prices against nearby sales. Automated valuation models (AVMs) estimate value using comparable sales, public records, and neighborhood data.
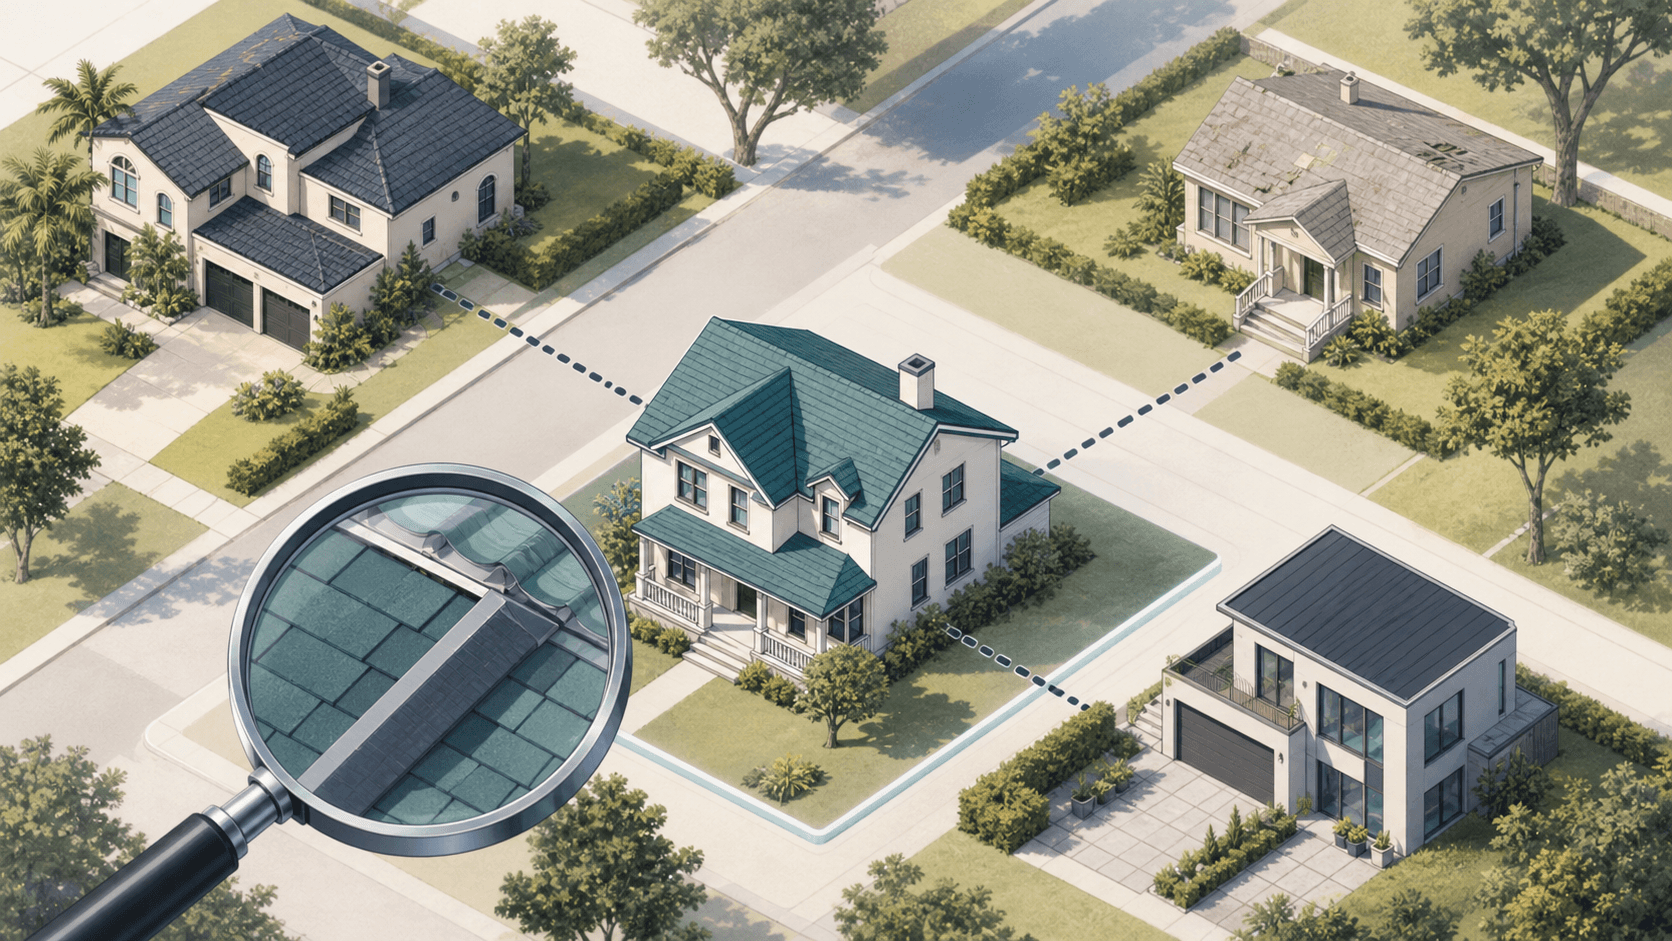
A comparative market analysis (CMA) typically uses 3 to 6 comps sold within 3 to 6 months nearby, adjusted for size, condition, and features.
Pricing tool | What you get |
|---|---|
AVM | Automated value estimate |
CMA | Agent's opinion using adjusted comparisons |
Formal appraisal | Licensed appraiser's valuation |
Before using an estimate to shape your offer, check whether the comparisons reflect the home's current condition.
AI for Reviewing Disclosures and Inspection Reports
Seller disclosures report known defects, flood history, and other conditions that could affect your purchase. Your experience owning a home helps, but dense paperwork can still hide details.
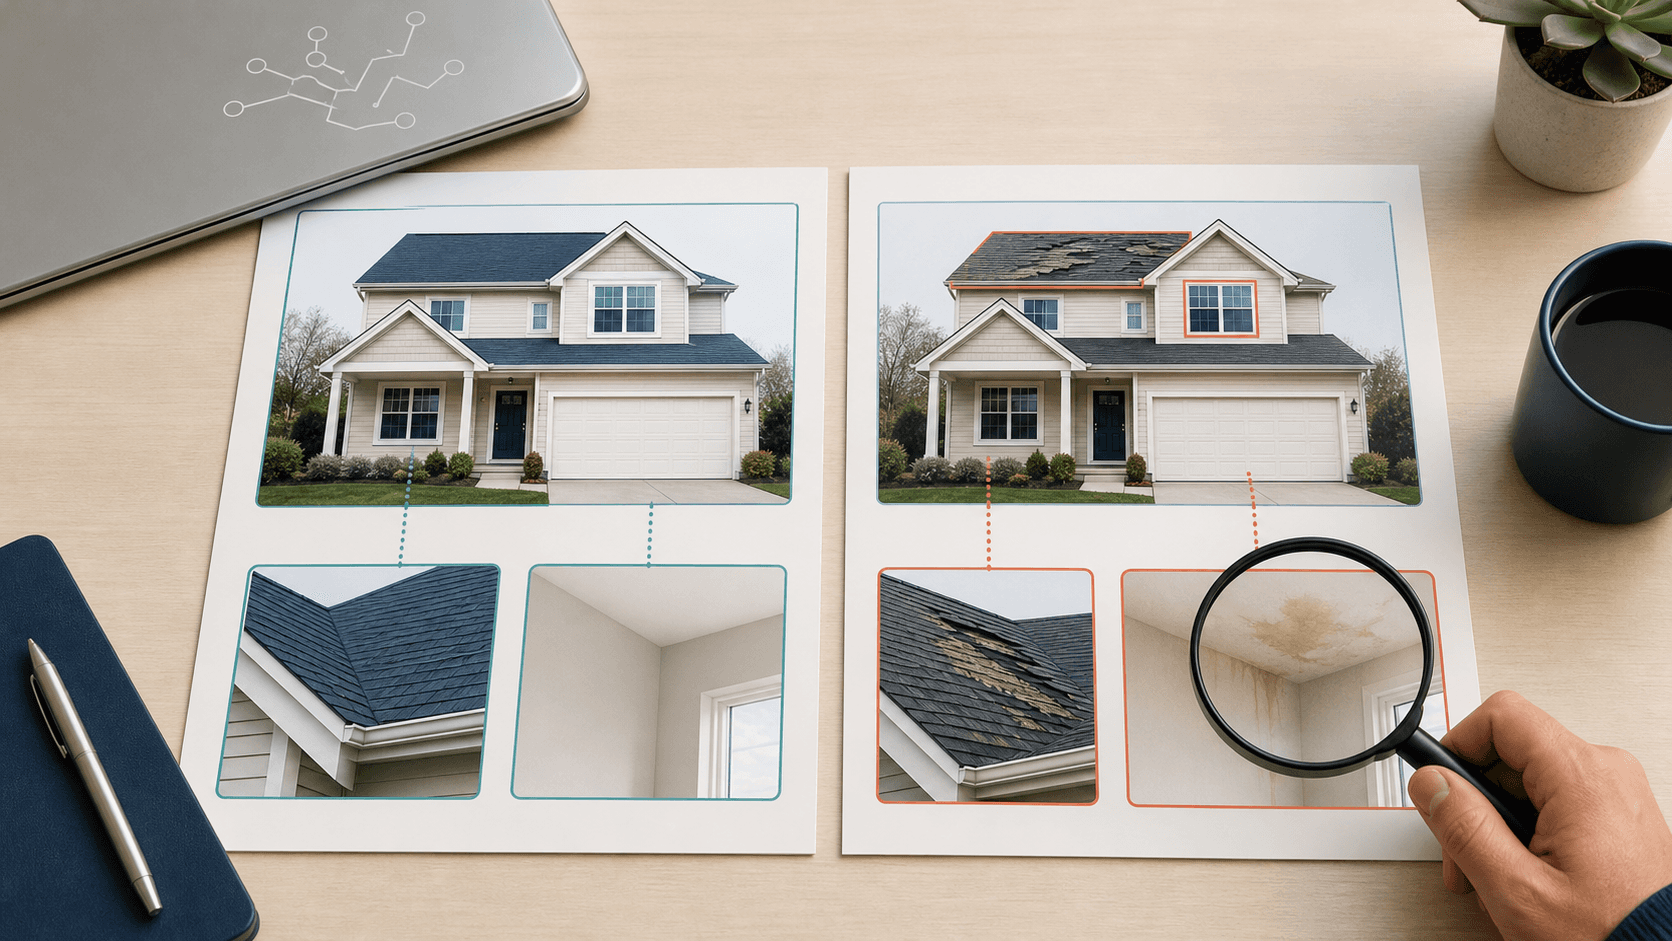
Ask your AI realtor tool to compare disclosures with the inspection report and flag:
Prior water intrusion with no documented repair.
Conflicting statements about roof age or condition.
Areas the inspector could not access.
Request page references so you can verify each flag. AI can spot wording and patterns, but your licensed inspector should handle home inspections for physical concerns, and your attorney should review binding documents.
What AI Cannot Do in a Real Estate Transaction
Your last purchase gives you context, but local rules, customs, and a different seller can change your next deal. AI cannot reliably supply the judgment those differences require.
Questions about whether AI will replace real estate agents miss the point here: an AI realtor tool cannot provide legal advice tailored to you or replace your judgment during live negotiations. Treat generated contract language as unverified text. The tool cannot take responsibility for a binding purchase contract.
Have a licensed agent or broker prepare, negotiate, and submit your offer with your approval. Bring legal questions about your obligations to your own attorney.
The Role of the Licensed Professional Alongside AI
An AI realtor tool can support your search, but licensed representation gives you someone to work through tradeoffs with the seller’s agent, especially when your next purchase depends on selling your current home.
Ask your agent to help you:
Shape your offer around competing bids and your moving timeline.
Negotiate price and repairs with supporting evidence.
Weigh contingencies against the risk of losing your deposit.
Resolve open terms with your lender and title team before closing.
When a counteroffer or inspection changes the deal, your agent can help you decide how to respond.
Prequalification vs. Pre-Approval: What AI Can and Cannot Tell You
If you still carry a mortgage on your current home, an AI realtor’s affordability estimate is only a starting point.
Prequalification versus pre-approval differ: instant prequalification gives you an informal estimate based on self-reported finances, without a hard credit check.
Verified pre-approval involves lender document review and typically a hard credit pull, giving you a conditional pre-approval letter.
Most sellers want verified pre-approval before taking your offer seriously; some require it before confirming a showing. AI can help you estimate your budget, but only a lender can complete the process of getting pre-approved and issue that letter after reviewing your finances.
How to Use AI When Making an Offer
Before making an offer call, use an AI realtor tool to build a brief you can question:
Compare AI-selected comparable sales with the listing price. Ask which property differences explain the gap.
Check the evidence behind AI claims about your bargaining power.
Separate pricing drivers, such as recent updates, from features you personally value.
Turn disclosure findings into unresolved questions for your licensed broker.
Bring your walk-away price and lessons from your previous purchase. Use the brief to discuss terms; your broker prepares the binding offer for your approval and submits it.
How Homa Combines AI Guidance with Licensed Representation
Homa pairs AI guidance with licensed representation for buyers in Florida and Texas through Homa Realty, Inc., offering an alternative for those researching buying a house without an agent. For your next purchase, its AI realtor tools support home analysis with the Homa Estimate, offer estimates using comparable sales and bargaining power, and disclosure review, with broker support through closing.
Licensed brokers draft, negotiate, and submit your offers. Agents earn the same per transaction regardless of your purchase price.
Your estimated Homa Credit is up to approximately 2%, after Homa’s fee of 1% or $4,995, whichever is greater. Final amounts depend on deal terms, your lender, and market conditions.
Final thoughts on Making AI Part of Your Next Purchase
Your experience still matters with an AI realtor tool. Let AI help narrow your search, not set your limits. Keep your budget firm and review offer terms with your licensed broker.
FAQ
Can you use Homa’s AI realtor tools if you need to sell your current home before buying again?
Yes, but you’ll need separate representation for your sale because Homa serves buyers only. Tell your licensed Homa broker that your purchase depends on selling, so you can discuss a home-sale contingency and closing dates before submitting an offer.
Should you lower your offer if the Homa Estimate is below the asking price?
Not automatically; use the gap as a reason to check the evidence with your licensed Homa broker. Ask whether the comparable sales reflect recent renovations, property condition, and current competition, then choose your offer price and walk-away limit.
How do you calculate the Homa Credit for your next purchase?
Subtract Homa’s fee, which is 1% of the purchase price or $4,995, whichever is greater, from the seller-paid buyer’s-agent commission. Any remaining amount is your estimated Homa Credit. Your final usable credit depends on deal terms and lender limits; it cannot fund your down payment.
Can you switch to Homa if you already signed with the agent from your last purchase?
You may be able to switch, but check your current buyer agreement first. An exclusive agreement must expire or be cancelled before Homa can work with you; if you already signed a purchase contract through that agent, Homa usually cannot take over that deal.
You're buying again, and an AI price estimate looks like a quick way to settle on an offer. But does it account for the home's condition, and are those nearby sales actually good comparisons? An ai realtor tool is useful when you can question its evidence. Use it to prepare your pricing and paperwork questions, while your licensed broker handles the binding offer with your approval.
TLDR:
Use AI realtor tools for your next purchase, but leave binding offers to a licensed broker.
Check your price estimate against 3 to 6 nearby comparable sales from the past 3 to 6 months.
Ask AI to flag disclosure and inspection conflicts, with page references you can verify.
Get your verified pre-approval from a lender. AI budget estimates cannot replace it.
Homa pairs AI home analysis with licensed representation for your purchase in Florida or Texas.
What "AI Realtor" Actually Means
“AI realtor” is shorthand for tech that helps you buy a home, not a real estate license or professional designation. If you’re buying again, these tools can help you check asking prices and review disclosures before you discuss findings with your broker. Examples include a search assistant that turns your wish list into property matches, an automated home-value estimator, or a document tool that flags conflicting roof details in your disclosures and inspection report.
Some tools turn your preferences into listing results. Others help you compare prices or review property documents. Some offer guidance alongside licensed professionals, who handle representation and transaction work, part of a broader shift toward AI-powered home buying.
When comparing AI realtor services, check what the software does, what requires a licensed professional, and who is responsible for your transaction.
How Buyers Are Already Using AI in Their Home Search
AI realtor tools can help with familiar homebuying tasks, but buyer interest is not proof of completed AI-only purchases. In a June 2026 Veterans United Home Loans survey, 53% of prospective homebuyers were comfortable buying without direct human involvement; 68% trusted AI-based mortgage information.
For your next purchase, practical uses include:
Comparing your previous lender with other options before you make calls.
Comparing loan options against how long you plan to own.
Organizing your paperwork as it arrives.
Start with a task that took too much time during your last purchase.
AI for Home Search and Discovery
Traditional MLS filters use fixed criteria, such as price and bedroom count. AI realtor search tools can let you describe your next home in plain English, with feeds that adapt as you browse.
Use what you learned from your last purchase: “I need desk space outside the bedrooms and less yard maintenance.” Keep your budget ceiling firm.
Tools that learn your preferences can suggest homes beyond your original filters, including listings with unexpected wording for usable space. Check suggestions against listing details: a breakfast nook may still make a poor office.
AI for Home Valuation and Pricing
For your next purchase, AI pricing tools can check asking prices against nearby sales. Automated valuation models (AVMs) estimate value using comparable sales, public records, and neighborhood data.
A comparative market analysis (CMA) typically uses 3 to 6 comps sold within 3 to 6 months nearby, adjusted for size, condition, and features.
Pricing tool | What you get |
|---|---|
AVM | Automated value estimate |
CMA | Agent's opinion using adjusted comparisons |
Formal appraisal | Licensed appraiser's valuation |
Before using an estimate to shape your offer, check whether the comparisons reflect the home's current condition.
AI for Reviewing Disclosures and Inspection Reports
Seller disclosures report known defects, flood history, and other conditions that could affect your purchase. Your experience owning a home helps, but dense paperwork can still hide details.
Ask your AI realtor tool to compare disclosures with the inspection report and flag:
Prior water intrusion with no documented repair.
Conflicting statements about roof age or condition.
Areas the inspector could not access.
Request page references so you can verify each flag. AI can spot wording and patterns, but your licensed inspector should handle home inspections for physical concerns, and your attorney should review binding documents.
What AI Cannot Do in a Real Estate Transaction
Your last purchase gives you context, but local rules, customs, and a different seller can change your next deal. AI cannot reliably supply the judgment those differences require.
Questions about whether AI will replace real estate agents miss the point here: an AI realtor tool cannot provide legal advice tailored to you or replace your judgment during live negotiations. Treat generated contract language as unverified text. The tool cannot take responsibility for a binding purchase contract.
Have a licensed agent or broker prepare, negotiate, and submit your offer with your approval. Bring legal questions about your obligations to your own attorney.
The Role of the Licensed Professional Alongside AI
An AI realtor tool can support your search, but licensed representation gives you someone to work through tradeoffs with the seller’s agent, especially when your next purchase depends on selling your current home.
Ask your agent to help you:
Shape your offer around competing bids and your moving timeline.
Negotiate price and repairs with supporting evidence.
Weigh contingencies against the risk of losing your deposit.
Resolve open terms with your lender and title team before closing.
When a counteroffer or inspection changes the deal, your agent can help you decide how to respond.
Prequalification vs. Pre-Approval: What AI Can and Cannot Tell You
If you still carry a mortgage on your current home, an AI realtor’s affordability estimate is only a starting point.
Prequalification versus pre-approval differ: instant prequalification gives you an informal estimate based on self-reported finances, without a hard credit check.
Verified pre-approval involves lender document review and typically a hard credit pull, giving you a conditional pre-approval letter.
Most sellers want verified pre-approval before taking your offer seriously; some require it before confirming a showing. AI can help you estimate your budget, but only a lender can complete the process of getting pre-approved and issue that letter after reviewing your finances.
How to Use AI When Making an Offer
Before making an offer call, use an AI realtor tool to build a brief you can question:
Compare AI-selected comparable sales with the listing price. Ask which property differences explain the gap.
Check the evidence behind AI claims about your bargaining power.
Separate pricing drivers, such as recent updates, from features you personally value.
Turn disclosure findings into unresolved questions for your licensed broker.
Bring your walk-away price and lessons from your previous purchase. Use the brief to discuss terms; your broker prepares the binding offer for your approval and submits it.
How Homa Combines AI Guidance with Licensed Representation
Homa pairs AI guidance with licensed representation for buyers in Florida and Texas through Homa Realty, Inc., offering an alternative for those researching buying a house without an agent. For your next purchase, its AI realtor tools support home analysis with the Homa Estimate, offer estimates using comparable sales and bargaining power, and disclosure review, with broker support through closing.
Licensed brokers draft, negotiate, and submit your offers. Agents earn the same per transaction regardless of your purchase price.
Your estimated Homa Credit is up to approximately 2%, after Homa’s fee of 1% or $4,995, whichever is greater. Final amounts depend on deal terms, your lender, and market conditions.
Final thoughts on Making AI Part of Your Next Purchase
Your experience still matters with an AI realtor tool. Let AI help narrow your search, not set your limits. Keep your budget firm and review offer terms with your licensed broker.
FAQ
Can you use Homa’s AI realtor tools if you need to sell your current home before buying again?
Yes, but you’ll need separate representation for your sale because Homa serves buyers only. Tell your licensed Homa broker that your purchase depends on selling, so you can discuss a home-sale contingency and closing dates before submitting an offer.
Should you lower your offer if the Homa Estimate is below the asking price?
Not automatically; use the gap as a reason to check the evidence with your licensed Homa broker. Ask whether the comparable sales reflect recent renovations, property condition, and current competition, then choose your offer price and walk-away limit.
How do you calculate the Homa Credit for your next purchase?
Subtract Homa’s fee, which is 1% of the purchase price or $4,995, whichever is greater, from the seller-paid buyer’s-agent commission. Any remaining amount is your estimated Homa Credit. Your final usable credit depends on deal terms and lender limits; it cannot fund your down payment.
Can you switch to Homa if you already signed with the agent from your last purchase?
You may be able to switch, but check your current buyer agreement first. An exclusive agreement must expire or be cancelled before Homa can work with you; if you already signed a purchase contract through that agent, Homa usually cannot take over that deal.
Find your home.
Get up to 2% back.
Search homes, schedule tours, make smarter offers, and get thousands back at closing with Homa
Find your home.
Get up to 2% back.
Search homes, schedule tours, make smarter offers, and get thousands back at closing with Homa
Find your home.
Get up to 2% back.
Search homes, schedule tours, make smarter offers, and get thousands back at closing with Homa


