
Most repeat buyers know to negotiate the price. Fewer know that a seller concession and a commission rebate are separate line items, and you can use both on the same transaction. On the right deal, your out-of-pocket at closing can get very close to zero without touching your down payment. Getting there means working a few angles at once, and this post lays out exactly how to do that.
TLDR:
Raising your credit score to 760+ before applying can save over $64,000 on a $400,000 mortgage versus a score near 700.
You can stack a seller concession and a commission rebate on the same deal. They're separate line items that don't cancel each other out.
Getting 3+ Loan Estimates within a 45-day window can save you $600 to $1,200 per year, with one credit inquiry instead of several.
Homes sitting 60+ days on market signal seller fatigue; that's when concession requests that would get rejected at listing become realistic.
Homa is a buyer-only brokerage in FL, TX, and CA that keeps 1% (min. $4,995) and returns the rest of the buyer's-agent commission as a closing credit.
What It Actually Costs to Buy a House
On a $500,000 home with 10% down, you could easily need $70,000 or more liquid before you move a single box. Most buyers budget carefully for the down payment, then get caught off guard by everything else. For a full breakdown of what to expect, see our guide on how much money to buy a house.
Here's a realistic breakdown of what you're typically looking at:
Down payment: 3% to 20% of the purchase price, depending on your loan type
Closing costs: 2% to 5% of the purchase price, covering lender fees, title insurance, taxes, and more
Prepaid items: homeowners insurance, property taxes, and prepaid mortgage interest due at closing
Inspection fees: usually $300 to $600 for a general inspection, more for specialized ones
Moving costs: easily $1,000 to $5,000 depending on distance and how much stuff you own
Saving money on a purchase requires working multiple angles at once, beyond hunting for a lower purchase price.
How Your Credit Score Affects What You Pay
Your credit score is one of the few variables you can actually move before you buy. Lenders use tiered pricing, so a score of 760 or above typically unlocks the best available rates, while dropping to 700 or below costs you noticeably more each month for the life of the loan.
The spread matters more than most buyers realize. On a $400,000 mortgage, the difference between a 6.5% and a 7.2% rate adds roughly $180 per month. Over 30 years, that's over $64,000. A negotiation tactic might save you $3,000 at closing. Improving your score before applying can do multiples of that.
A few moves that actually help in the months before you apply:
Pay down revolving balances to below 30% of your credit limit, since utilization ratio is one of the fastest levers you can pull.
Avoid opening new credit accounts, as hard inquiries and new accounts both ding your score temporarily.
Check your credit report for errors and dispute any inaccurate derogatory marks before a lender ever sees them.
Stay current on every account, because even one 30-day late payment can drop your score by a meaningful amount.
How to Shop for the Best Mortgage Rate
Historically, many buyers have spent weeks comparing granite countertops and maybe 20 minutes comparing lenders. That's backwards. According to Freddie Mac research, homebuyers can potentially save $600 to $1,200 per year by getting mortgage offers from multiple lenders.
Get at least three Loan Estimates within a 45-day window. Credit bureaus treat multiple mortgage inquiries in that period as a single pull, so your score takes one hit instead of several.
When comparing offers, look beyond the interest rate:
APR rolls in fees, making it a cleaner apples-to-apples number than the rate alone
Points and origination fees can lower your rate upfront but cost real money at closing
Closing cost estimates vary by lender, sometimes by thousands of dollars on the same loan amount
A prequalification rate is an estimate based on self-reported info. A Loan Estimate is a formal document issued after a lender reviews your actual financials. Only locked offers protect you from rate movement before closing.
Choosing the Right Loan Type Can Reduce What You Bring to Closing
Loan type shapes how much you need at the table before you even start negotiating. Each program sets its own ceiling on seller concessions, which determines how much of your closing costs a seller can legally cover.
Loan Type | Min. Down Payment | Max. Seller Concessions |
|---|---|---|
Conventional | 3% | 3% to 9% depending on LTV |
FHA | 3.5% | |
VA | 0% | Up to 4% |
USDA | 0% | Up to 6% |
VA and USDA loans require nothing down, which alone can free up tens of thousands in cash. Pair either with a seller concession close to the program maximum and your out-of-pocket at closing shrinks considerably. The loan type you choose sets the outer limit of what's possible before a single negotiation happens.
How Seller Concessions Work and How to Negotiate Them
Seller concessions are closing costs the seller agrees to pay on your behalf. Instead of lowering the purchase price, the seller covers a chunk of what you'd owe at the closing table. For repeat buyers, the practical difference matters: a price reduction shows up in public sale records and can pull down comps for the seller's neighbors. A concession doesn't. Sellers often prefer it for exactly that reason.
The ask is most effective when a home has been sitting. Longer days on market means more negotiating power. In cooler conditions, requesting 2% to 3% in seller-paid closing costs is reasonable, and sellers motivated to close will frequently agree instead of relisting.
How you frame the request matters. A higher purchase price with a matching seller concession is sometimes more palatable than a straight price cut, because the seller's net proceeds land in a similar place while the official sale price stays intact. Your lender needs to approve this structure, and the concession can't exceed your actual closing costs under Fannie Mae guidelines. Excess amounts get treated as sales concessions and reduce your loan basis. Run the numbers by your lender before you write the offer.
What a Commission Rebate Is and How to Get One
A commission rebate is money a buyer's agent returns to their client at closing, drawn from the commission the seller is already paying. It typically lands as a credit on the settlement statement, applied toward closing costs or a rate buy-down.
Commission rebates are legal in ~40 states, with a handful still restricting the practice. The IRS treats these rebates as a reduction in the purchase price, not as taxable income, which is one of the cleaner outcomes in real estate tax law. A lower purchase price does mean a lower cost basis, so check with your CPA on the long-term implications when you sell.
Most lenders allow a rebate to count toward closing costs as long as it's disclosed upfront. Confirm with your lender early, since rebates cannot go toward your down payment under standard lending guidelines. Whatever you don't use for closing costs can typically be applied to buying down your rate.
To get one, look for brokerages that operate on a buyer commission rebate model from the start, with the amount and structure spelled out in your buyer agreement before you tour a single home.
How to Stack a Commission Rebate With Seller Concessions
Most buyers know about seller concessions. Some know about commission rebates. Very few realize you can use both on the same transaction.
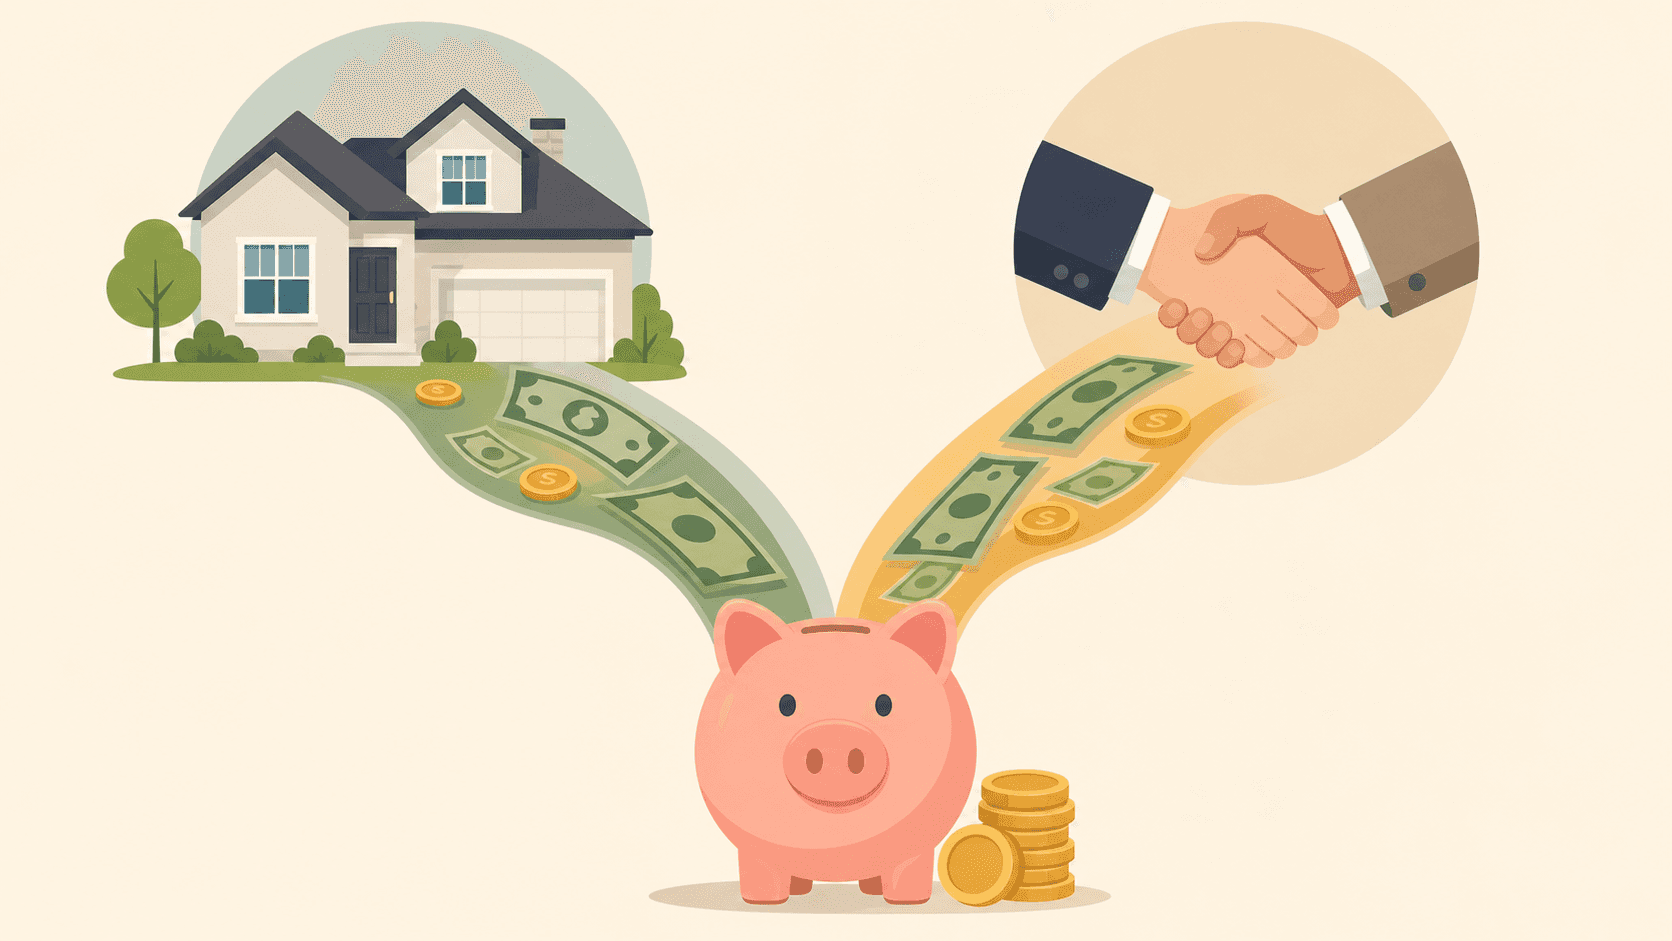
They're separate line items on the settlement statement. The seller concession comes from the seller's side of the ledger; the commission rebate comes from the buyer's broker. They don't offset each other. Both apply toward your closing costs, subject to your loan program's cap on total seller contributions.
Here's how it plays out on a $450,000 home with a conventional loan at 90% LTV:
Item | Amount |
|---|---|
Estimated closing costs | $11,000 (~2.5%) |
Seller concession (3%) | $13,500 |
Commission rebate (~2%) | $9,000 |
Net out-of-pocket at closing | ~$0 (excess applied to rate buy-down) |
The seller concession covers closing costs and prepaids; any remaining commission rebate goes toward mortgage rate buydown. Confirm the structure with your lender before writing the offer, since lenders cap how much total seller contribution can count toward financing concessions. Any excess over your actual closing costs gets redirected, not handed back as cash.
The key is sequencing: negotiate the seller concession in the offer, then confirm your broker's rebate amount before closing.
Reading a Seller's Disclosure Before Making an Offer
You've read a seller's disclosure before, but it's worth being more systematic the second time around. State requirements vary — in Florida and Texas, sellers must disclose anything they know that could affect value or desirability — and the word "known" does a lot of work. Read carefully and verify anything that sounds vague.
A missed disclosure item can cost you far more than any concession you negotiated. Here's what to review carefully before writing an offer:
Water intrusion and mold: any history of leaks, flooding inside the home, or moisture issues is worth a follow-up inspection, even if marked as "repaired"
Roof age and condition: older roofs affect insurance costs and insurability in Florida especially, where insurers review roof age carefully
Foundation concerns: cracks, settling, or prior repairs are red flags that general inspectors sometimes miss without a structural specialist
Unpermitted work: additions or renovations done without permits can block future financing and become your legal problem after closing
Flooding history: prior flood claims or FEMA flood zone designations should change what you pay for flood insurance, or whether you make an offer at all
HOA and CDD liabilities: special assessments, pending litigation, or deferred maintenance funds can mean unexpected costs that never appear in the list price
If the disclosure is thin or leans heavily on "unknown" responses, request more documentation before you proceed.
Down Payment Amount and PMI: The Trade-Off Buyers Need to Understand
The 20% down payment threshold is real, but it's not always the right call. PMI on a conventional loan typically runs 0.5% to 1.5% of the loan amount annually. On a $400,000 loan, that's $2,000 to $6,000 per year until you reach 20% equity. That stings, but tying up an extra $40,000 to $60,000 in your home has its own cost: that cash can't cover repairs, fund a rate buy-down, or sit in an account earning interest.
In a higher-rate environment, using extra cash to buy down your rate often beats a larger down payment. A 1% rate reduction on a $400,000 loan saves roughly $220 per month, which can exceed your PMI cost while keeping cash liquid.
FHA loans work differently. They carry an upfront mortgage insurance premium plus an annual premium that, for most borrowers putting down less than 10%, lasts the life of the loan. Unlike conventional PMI, it doesn't cancel when you hit 20% equity, so factor that permanence into your long-run cost comparison.
A lower down payment with PMI can be the rational choice if you have strong monthly cash flow, a competitive rate, and near-term plans to refinance once equity builds. The real threshold to weigh is whether the monthly PMI cost exceeds the return you'd get from deploying that cash elsewhere.
The Timing and Market Condition Angle
Timing a purchase around life circumstances is hard. But if you have any flexibility at all, market conditions and seasonal patterns meaningfully affect how much you can ask for, and what sellers will actually give.
Inventory peaks in spring and summer, which brings competition and tighter negotiating room. Late fall and winter tell a different story. Sellers listing in December or January are typically motivated. Fewer buyers are active, properties sit longer, and that negotiating position is yours to use.
Two local data points matter more than national headlines: days on market and the list-to-sale ratio.
A home that has been sitting 60-plus days is a different negotiation than one that just listed. Extended market time signals seller fatigue, and concession requests that would get laughed at in week one become reasonable in week eight.
A list-to-sale ratio above 100% means homes are selling above asking, which compresses your negotiating room. A ratio below 98% in your target area suggests sellers are routinely accepting less than list.
Both numbers are available through your agent or your local MLS.
One practical note: price reductions and concessions are not interchangeable negotiating tools. In a softening market, a price cut makes mathematical sense and reduces what you finance. A concession preserves the purchase price on paper while reducing your upfront cash need. Which one serves you better depends on your loan program limits and your specific cash situation at closing.
How AI Tools Are Changing the Home Buying Research Process
AI tools have genuinely moved into home-buying research, and for repeat buyers who already know the process, they save real time. Tools like HouseCanary for automated valuation models, Perplexity for pulling recent comparable sales, and Homa's built-in offer estimator for modeling offer ranges are all areas where AI can surface useful information faster than manually pulling records or waiting on an agent to run numbers. Disclosure document review is another use case, and AI can flag items worth a follow-up faster than reading line by line.
Where AI earns its keep:
Valuation estimates based on recent comparable sales and local market data
Identifying how long a home has sat on market and how that affects your negotiating position
Flagging items in a seller's disclosure that warrant follow-up inspection
Modeling offer ranges and showing the comps behind the suggested number
Where a licensed broker still has to be in the room: drafting the purchase contract, negotiating directly with the listing agent, advising on counter-offer strategy, and submitting anything binding. AI output is guidance. The contract is a legal document, and no AI tool currently signs off on one.
AI compresses research time without replacing judgment. An AI-generated offer range tells you where to start thinking; a licensed agent tells you whether the market, the seller's situation, and your specific loan structure make that number viable. Treat AI analysis as a well-researched starting point, not a final answer.
How Homa Returns Most of the Buyer's Commission Back at Closing
Homa is a licensed buyer-only brokerage operating in Florida, Texas, and California. The model is straightforward: the seller pays the buyer's-agent commission, Homa keeps 1% of the purchase price (or $4,995, whichever is greater), and the rest comes back to you at closing as the Homa Credit.
On a $500,000 home where the seller offers a 3% buyer's-agent commission, that's $15,000 in commission. Homa keeps $5,000. You receive an estimated $10,000 credit toward closing costs, prepaids, or a rate buy-down.
That credit is separate from any seller concession a licensed Homa agent negotiates on your behalf. Stack both, and you're working the same math covered earlier in this article. Final amounts depend on deal terms, your lender, and market conditions, so treat the Estimated Homa Credit as a starting point, not a guarantee.
Browsing is free. Tours are free. Homa is paid only if you close.
Final Thoughts on How to Save Money Buying a House
Saving money on a home purchase is less about finding a deal and more about understanding where your costs come from. Your credit score, down payment strategy, loan type, and agent structure all affect what you pay. Get clear on each one before you write an offer, and you go in with a real advantage.
FAQ
How do I get a commission rebate when buying a home, and is it legal in my state?
Commission rebates are legal in roughly 40 states. Your buyer's broker returns a portion of the seller-paid commission to you at closing as a credit toward closing costs, prepaids, or a rate buy-down. To get one, look for a brokerage that structures the rebate into your buyer agreement upfront, with the amount spelled out before you tour anything. With Homa, the model is explicit: the seller pays the buyer's-agent commission, Homa keeps 1% of the purchase price (or $4,995, whichever is greater), and the remainder (up to roughly 2%) comes back to you at closing as the Homa Credit.
Can I use a buyer's agent commission rebate to cover closing costs, or does my lender block it?
Almost all lenders allow a commission rebate to count toward closing costs, as long as it's disclosed upfront. Describe it to your lender as a commission rebate from your broker and confirm early in the process. The one firm limit: it cannot go toward your down payment under standard lending guidelines. Anything left after closing costs and prepaids are covered can typically be applied to buying down your mortgage rate.
How do I negotiate seller concessions when buying a house, and how much can I ask for?
Seller concessions are most effective when a home has been sitting. At 60-plus days on market, you have real negotiating power to request 2% to 3% in seller-paid closing costs without much pushback. The ceiling depends on your loan type: FHA and USDA allow up to 6%, VA up to 4%, and conventional loans allow 3% to 9% depending on your loan-to-value ratio. One structure worth knowing: a slightly higher purchase price paired with a matching seller concession sometimes lands better with sellers than a straight price cut, since their net proceeds end up similar and the official sale price stays intact.
Can I stack a commission rebate and seller concessions on the same home purchase?
Yes. They're separate line items on the settlement statement and don't cancel each other out. The seller concession comes from the seller's side; the commission rebate comes from your broker. See the stacking example earlier for a full breakdown. Just confirm the combined total with your lender before writing the offer, since loan programs cap how much total seller contribution counts toward financing.
What should I look for in a seller's disclosure before making an offer?
Focus on the items that signal hidden cost, beyond obvious damage: water intrusion history (even marked "repaired"), roof age, unpermitted additions, prior flood claims, and any HOA special assessments. In Florida and Texas, sellers must disclose anything they know that could affect value, but "known" is the operative word, so treat thin disclosures or heavy use of "unknown" responses as a reason to request more documentation before you proceed.
Most repeat buyers know to negotiate the price. Fewer know that a seller concession and a commission rebate are separate line items, and you can use both on the same transaction. On the right deal, your out-of-pocket at closing can get very close to zero without touching your down payment. Getting there means working a few angles at once, and this post lays out exactly how to do that.
TLDR:
Raising your credit score to 760+ before applying can save over $64,000 on a $400,000 mortgage versus a score near 700.
You can stack a seller concession and a commission rebate on the same deal. They're separate line items that don't cancel each other out.
Getting 3+ Loan Estimates within a 45-day window can save you $600 to $1,200 per year, with one credit inquiry instead of several.
Homes sitting 60+ days on market signal seller fatigue; that's when concession requests that would get rejected at listing become realistic.
Homa is a buyer-only brokerage in FL, TX, and CA that keeps 1% (min. $4,995) and returns the rest of the buyer's-agent commission as a closing credit.
What It Actually Costs to Buy a House
On a $500,000 home with 10% down, you could easily need $70,000 or more liquid before you move a single box. Most buyers budget carefully for the down payment, then get caught off guard by everything else. For a full breakdown of what to expect, see our guide on how much money to buy a house.
Here's a realistic breakdown of what you're typically looking at:
Down payment: 3% to 20% of the purchase price, depending on your loan type
Closing costs: 2% to 5% of the purchase price, covering lender fees, title insurance, taxes, and more
Prepaid items: homeowners insurance, property taxes, and prepaid mortgage interest due at closing
Inspection fees: usually $300 to $600 for a general inspection, more for specialized ones
Moving costs: easily $1,000 to $5,000 depending on distance and how much stuff you own
Saving money on a purchase requires working multiple angles at once, beyond hunting for a lower purchase price.
How Your Credit Score Affects What You Pay
Your credit score is one of the few variables you can actually move before you buy. Lenders use tiered pricing, so a score of 760 or above typically unlocks the best available rates, while dropping to 700 or below costs you noticeably more each month for the life of the loan.
The spread matters more than most buyers realize. On a $400,000 mortgage, the difference between a 6.5% and a 7.2% rate adds roughly $180 per month. Over 30 years, that's over $64,000. A negotiation tactic might save you $3,000 at closing. Improving your score before applying can do multiples of that.
A few moves that actually help in the months before you apply:
Pay down revolving balances to below 30% of your credit limit, since utilization ratio is one of the fastest levers you can pull.
Avoid opening new credit accounts, as hard inquiries and new accounts both ding your score temporarily.
Check your credit report for errors and dispute any inaccurate derogatory marks before a lender ever sees them.
Stay current on every account, because even one 30-day late payment can drop your score by a meaningful amount.
How to Shop for the Best Mortgage Rate
Historically, many buyers have spent weeks comparing granite countertops and maybe 20 minutes comparing lenders. That's backwards. According to Freddie Mac research, homebuyers can potentially save $600 to $1,200 per year by getting mortgage offers from multiple lenders.
Get at least three Loan Estimates within a 45-day window. Credit bureaus treat multiple mortgage inquiries in that period as a single pull, so your score takes one hit instead of several.
When comparing offers, look beyond the interest rate:
APR rolls in fees, making it a cleaner apples-to-apples number than the rate alone
Points and origination fees can lower your rate upfront but cost real money at closing
Closing cost estimates vary by lender, sometimes by thousands of dollars on the same loan amount
A prequalification rate is an estimate based on self-reported info. A Loan Estimate is a formal document issued after a lender reviews your actual financials. Only locked offers protect you from rate movement before closing.
Choosing the Right Loan Type Can Reduce What You Bring to Closing
Loan type shapes how much you need at the table before you even start negotiating. Each program sets its own ceiling on seller concessions, which determines how much of your closing costs a seller can legally cover.
Loan Type | Min. Down Payment | Max. Seller Concessions |
|---|---|---|
Conventional | 3% | 3% to 9% depending on LTV |
FHA | 3.5% | |
VA | 0% | Up to 4% |
USDA | 0% | Up to 6% |
VA and USDA loans require nothing down, which alone can free up tens of thousands in cash. Pair either with a seller concession close to the program maximum and your out-of-pocket at closing shrinks considerably. The loan type you choose sets the outer limit of what's possible before a single negotiation happens.
How Seller Concessions Work and How to Negotiate Them
Seller concessions are closing costs the seller agrees to pay on your behalf. Instead of lowering the purchase price, the seller covers a chunk of what you'd owe at the closing table. For repeat buyers, the practical difference matters: a price reduction shows up in public sale records and can pull down comps for the seller's neighbors. A concession doesn't. Sellers often prefer it for exactly that reason.
The ask is most effective when a home has been sitting. Longer days on market means more negotiating power. In cooler conditions, requesting 2% to 3% in seller-paid closing costs is reasonable, and sellers motivated to close will frequently agree instead of relisting.
How you frame the request matters. A higher purchase price with a matching seller concession is sometimes more palatable than a straight price cut, because the seller's net proceeds land in a similar place while the official sale price stays intact. Your lender needs to approve this structure, and the concession can't exceed your actual closing costs under Fannie Mae guidelines. Excess amounts get treated as sales concessions and reduce your loan basis. Run the numbers by your lender before you write the offer.
What a Commission Rebate Is and How to Get One
A commission rebate is money a buyer's agent returns to their client at closing, drawn from the commission the seller is already paying. It typically lands as a credit on the settlement statement, applied toward closing costs or a rate buy-down.
Commission rebates are legal in ~40 states, with a handful still restricting the practice. The IRS treats these rebates as a reduction in the purchase price, not as taxable income, which is one of the cleaner outcomes in real estate tax law. A lower purchase price does mean a lower cost basis, so check with your CPA on the long-term implications when you sell.
Most lenders allow a rebate to count toward closing costs as long as it's disclosed upfront. Confirm with your lender early, since rebates cannot go toward your down payment under standard lending guidelines. Whatever you don't use for closing costs can typically be applied to buying down your rate.
To get one, look for brokerages that operate on a buyer commission rebate model from the start, with the amount and structure spelled out in your buyer agreement before you tour a single home.
How to Stack a Commission Rebate With Seller Concessions
Most buyers know about seller concessions. Some know about commission rebates. Very few realize you can use both on the same transaction.
They're separate line items on the settlement statement. The seller concession comes from the seller's side of the ledger; the commission rebate comes from the buyer's broker. They don't offset each other. Both apply toward your closing costs, subject to your loan program's cap on total seller contributions.
Here's how it plays out on a $450,000 home with a conventional loan at 90% LTV:
Item | Amount |
|---|---|
Estimated closing costs | $11,000 (~2.5%) |
Seller concession (3%) | $13,500 |
Commission rebate (~2%) | $9,000 |
Net out-of-pocket at closing | ~$0 (excess applied to rate buy-down) |
The seller concession covers closing costs and prepaids; any remaining commission rebate goes toward mortgage rate buydown. Confirm the structure with your lender before writing the offer, since lenders cap how much total seller contribution can count toward financing concessions. Any excess over your actual closing costs gets redirected, not handed back as cash.
The key is sequencing: negotiate the seller concession in the offer, then confirm your broker's rebate amount before closing.
Reading a Seller's Disclosure Before Making an Offer
You've read a seller's disclosure before, but it's worth being more systematic the second time around. State requirements vary — in Florida and Texas, sellers must disclose anything they know that could affect value or desirability — and the word "known" does a lot of work. Read carefully and verify anything that sounds vague.
A missed disclosure item can cost you far more than any concession you negotiated. Here's what to review carefully before writing an offer:
Water intrusion and mold: any history of leaks, flooding inside the home, or moisture issues is worth a follow-up inspection, even if marked as "repaired"
Roof age and condition: older roofs affect insurance costs and insurability in Florida especially, where insurers review roof age carefully
Foundation concerns: cracks, settling, or prior repairs are red flags that general inspectors sometimes miss without a structural specialist
Unpermitted work: additions or renovations done without permits can block future financing and become your legal problem after closing
Flooding history: prior flood claims or FEMA flood zone designations should change what you pay for flood insurance, or whether you make an offer at all
HOA and CDD liabilities: special assessments, pending litigation, or deferred maintenance funds can mean unexpected costs that never appear in the list price
If the disclosure is thin or leans heavily on "unknown" responses, request more documentation before you proceed.
Down Payment Amount and PMI: The Trade-Off Buyers Need to Understand
The 20% down payment threshold is real, but it's not always the right call. PMI on a conventional loan typically runs 0.5% to 1.5% of the loan amount annually. On a $400,000 loan, that's $2,000 to $6,000 per year until you reach 20% equity. That stings, but tying up an extra $40,000 to $60,000 in your home has its own cost: that cash can't cover repairs, fund a rate buy-down, or sit in an account earning interest.
In a higher-rate environment, using extra cash to buy down your rate often beats a larger down payment. A 1% rate reduction on a $400,000 loan saves roughly $220 per month, which can exceed your PMI cost while keeping cash liquid.
FHA loans work differently. They carry an upfront mortgage insurance premium plus an annual premium that, for most borrowers putting down less than 10%, lasts the life of the loan. Unlike conventional PMI, it doesn't cancel when you hit 20% equity, so factor that permanence into your long-run cost comparison.
A lower down payment with PMI can be the rational choice if you have strong monthly cash flow, a competitive rate, and near-term plans to refinance once equity builds. The real threshold to weigh is whether the monthly PMI cost exceeds the return you'd get from deploying that cash elsewhere.
The Timing and Market Condition Angle
Timing a purchase around life circumstances is hard. But if you have any flexibility at all, market conditions and seasonal patterns meaningfully affect how much you can ask for, and what sellers will actually give.
Inventory peaks in spring and summer, which brings competition and tighter negotiating room. Late fall and winter tell a different story. Sellers listing in December or January are typically motivated. Fewer buyers are active, properties sit longer, and that negotiating position is yours to use.
Two local data points matter more than national headlines: days on market and the list-to-sale ratio.
A home that has been sitting 60-plus days is a different negotiation than one that just listed. Extended market time signals seller fatigue, and concession requests that would get laughed at in week one become reasonable in week eight.
A list-to-sale ratio above 100% means homes are selling above asking, which compresses your negotiating room. A ratio below 98% in your target area suggests sellers are routinely accepting less than list.
Both numbers are available through your agent or your local MLS.
One practical note: price reductions and concessions are not interchangeable negotiating tools. In a softening market, a price cut makes mathematical sense and reduces what you finance. A concession preserves the purchase price on paper while reducing your upfront cash need. Which one serves you better depends on your loan program limits and your specific cash situation at closing.
How AI Tools Are Changing the Home Buying Research Process
AI tools have genuinely moved into home-buying research, and for repeat buyers who already know the process, they save real time. Tools like HouseCanary for automated valuation models, Perplexity for pulling recent comparable sales, and Homa's built-in offer estimator for modeling offer ranges are all areas where AI can surface useful information faster than manually pulling records or waiting on an agent to run numbers. Disclosure document review is another use case, and AI can flag items worth a follow-up faster than reading line by line.
Where AI earns its keep:
Valuation estimates based on recent comparable sales and local market data
Identifying how long a home has sat on market and how that affects your negotiating position
Flagging items in a seller's disclosure that warrant follow-up inspection
Modeling offer ranges and showing the comps behind the suggested number
Where a licensed broker still has to be in the room: drafting the purchase contract, negotiating directly with the listing agent, advising on counter-offer strategy, and submitting anything binding. AI output is guidance. The contract is a legal document, and no AI tool currently signs off on one.
AI compresses research time without replacing judgment. An AI-generated offer range tells you where to start thinking; a licensed agent tells you whether the market, the seller's situation, and your specific loan structure make that number viable. Treat AI analysis as a well-researched starting point, not a final answer.
How Homa Returns Most of the Buyer's Commission Back at Closing
Homa is a licensed buyer-only brokerage operating in Florida, Texas, and California. The model is straightforward: the seller pays the buyer's-agent commission, Homa keeps 1% of the purchase price (or $4,995, whichever is greater), and the rest comes back to you at closing as the Homa Credit.
On a $500,000 home where the seller offers a 3% buyer's-agent commission, that's $15,000 in commission. Homa keeps $5,000. You receive an estimated $10,000 credit toward closing costs, prepaids, or a rate buy-down.
That credit is separate from any seller concession a licensed Homa agent negotiates on your behalf. Stack both, and you're working the same math covered earlier in this article. Final amounts depend on deal terms, your lender, and market conditions, so treat the Estimated Homa Credit as a starting point, not a guarantee.
Browsing is free. Tours are free. Homa is paid only if you close.
Final Thoughts on How to Save Money Buying a House
Saving money on a home purchase is less about finding a deal and more about understanding where your costs come from. Your credit score, down payment strategy, loan type, and agent structure all affect what you pay. Get clear on each one before you write an offer, and you go in with a real advantage.
FAQ
How do I get a commission rebate when buying a home, and is it legal in my state?
Commission rebates are legal in roughly 40 states. Your buyer's broker returns a portion of the seller-paid commission to you at closing as a credit toward closing costs, prepaids, or a rate buy-down. To get one, look for a brokerage that structures the rebate into your buyer agreement upfront, with the amount spelled out before you tour anything. With Homa, the model is explicit: the seller pays the buyer's-agent commission, Homa keeps 1% of the purchase price (or $4,995, whichever is greater), and the remainder (up to roughly 2%) comes back to you at closing as the Homa Credit.
Can I use a buyer's agent commission rebate to cover closing costs, or does my lender block it?
Almost all lenders allow a commission rebate to count toward closing costs, as long as it's disclosed upfront. Describe it to your lender as a commission rebate from your broker and confirm early in the process. The one firm limit: it cannot go toward your down payment under standard lending guidelines. Anything left after closing costs and prepaids are covered can typically be applied to buying down your mortgage rate.
How do I negotiate seller concessions when buying a house, and how much can I ask for?
Seller concessions are most effective when a home has been sitting. At 60-plus days on market, you have real negotiating power to request 2% to 3% in seller-paid closing costs without much pushback. The ceiling depends on your loan type: FHA and USDA allow up to 6%, VA up to 4%, and conventional loans allow 3% to 9% depending on your loan-to-value ratio. One structure worth knowing: a slightly higher purchase price paired with a matching seller concession sometimes lands better with sellers than a straight price cut, since their net proceeds end up similar and the official sale price stays intact.
Can I stack a commission rebate and seller concessions on the same home purchase?
Yes. They're separate line items on the settlement statement and don't cancel each other out. The seller concession comes from the seller's side; the commission rebate comes from your broker. See the stacking example earlier for a full breakdown. Just confirm the combined total with your lender before writing the offer, since loan programs cap how much total seller contribution counts toward financing.
What should I look for in a seller's disclosure before making an offer?
Focus on the items that signal hidden cost, beyond obvious damage: water intrusion history (even marked "repaired"), roof age, unpermitted additions, prior flood claims, and any HOA special assessments. In Florida and Texas, sellers must disclose anything they know that could affect value, but "known" is the operative word, so treat thin disclosures or heavy use of "unknown" responses as a reason to request more documentation before you proceed.
Find your home.
Get up to 2% back.
Search homes, schedule tours, make smarter offers, and get thousands back at closing with Homa
Find your home.
Get up to 2% back.
Search homes, schedule tours, make smarter offers, and get thousands back at closing with Homa
Find your home.
Get up to 2% back.
Search homes, schedule tours, make smarter offers, and get thousands back at closing with Homa


