Looking for {{builder}} homes in {{city}}? Get back up to 2%
Looking for {{builder}} homes in {{city}}? Get back up to 2%
Looking for {{builder}} homes in {{city}}? Get back up to 2%
Buy your new home with Homa and get most of the buyer's agent commission back at closing, while having an experienced agent by your side every step of the way.
On-demand tours, experts at every step, and up to 2% back to lower your rate,
closing costs, or purchase price.
Buy your new home with Homa and get most of the buyer's agent commission back at closing, while having an experienced agent by your side every step of the way.
Available in California, Florida and Texas.

5.0
14,000+
14,000+
Registered home buyers
Your Homa credit
$15,000
based on $750k home

Your Homa credit
$15,000
based on $750k home

Your Homa credit
$15,000
based on $750k home
Your Homa credit
$15,000
based on $750k home
Why Homa
Why Homa
A better way to buy your new home.
A better way to buy your new home.
A better way to buy your new home.

Get up to 2% back
Get up to 2% back
Get most of the buyer's agent commission back at closing with your Homa Credit.
Get most of the buyer's agent commission back at closing with your Homa Credit.

An expert on your side
An expert on your side
Get guidance from an experienced agent who represents your interests, not the builder's.
Get guidance from an experienced agent who represents your interests, not the builder's.

From first tour to closing
From first tour to closing
Get help navigating builder contracts, upgrades, inspections, and every step of your purchase.
Get help navigating builder contracts, upgrades, inspections, and every step of your purchase.
before you visit
Contact us before visiting your {{builder}} home in {{city}}
Most builders require you to register your buyer's agent before your first visit. Connect with Homa first to protect your eligibility for up to 2% back at closing.
before you visit
Contact us before visiting your {{builder}} home in {{city}}
Most builders require you to register your buyer's agent before your first visit. Connect with Homa first to protect your eligibility for up to 2% back at closing.
before you visit
Contact us before visiting your {{builder}} home in {{city}}
Most builders require you to register your buyer's agent before your first visit. Connect with Homa first to protect your eligibility for up to 2% back at closing.
THE HOMA DIFFERENCE
THE HOMA DIFFERENCE
Builders look out for their interests. We look out for yours.
Builders look out for their interests. We look out for yours.
Builders look out for their interests. We look out for yours.
Representation
Representation
Representation
Expert guidance
Expert guidance
Expert guidance
Negotiation
Negotiation
Negotiation
Contracts
Contracts
Contracts
Money back at closing
Money back at closing
Money back at closing
{{Builder}}
{{Builder}}
{{Builder}}
{{Builder}}'s interests
{{Builder}}'s interests
{{Builder}}'s interests
{{Builder}}'s sales team
{{Builder}}'s sales team
{{Builder}}'s sales team
On your own
On your own
On your own
On your own
On your own
On your own
No agent commission rebate
No agent commission rebate
No agent commission rebate

Your interests
Your interests
Your interests
Your dedicated agent
Your dedicated agent
Your dedicated agent
Expert help
Expert help
Expert help
Expert guidance
Expert guidance
Expert guidance
Up to 2% back
Up to 2% back
Up to 2% back
If you buy directly from the builder, you most likely won't receive the commission they would otherwise pay a buyer's agent. By purchasing with Homa, you get expert representation and can receive most of that commission back as a credit at closing, saving you thousands. Just make sure to contact Homa before visiting a community, as many builders require you to register your agent before your first visit.
If you buy directly from the builder, you most likely won't receive the commission they would otherwise pay a buyer's agent. By purchasing with Homa, you get expert representation and can receive most of that commission back as a credit at closing, saving you thousands. Just make sure to contact Homa before visiting a community, as many builders require you to register your agent before your first visit.
YOUR POTENTIAL SAVINGS
YOUR POTENTIAL SAVINGS
See how much you could get back on your home.
See how much you could get back on your home.
See how much you could get back on your home.
Buying a new home doesn't mean leaving money on the table. See how much of the buyer's agent commission you could get back with Homa.
Lower your rate
Put your credit toward a rate buydown and lower your monthly payment and rate by up to 0.75%.
Reduce closing costs
Apply your credit to closing costs and keep more cash on hand.
Lower the price
Apply your credit directly to reduce the home’s purchase price.
Lower your rate
Put your credit toward a rate buydown and lower your monthly payment and rate by up to 0.75%.
Reduce closing costs
Apply your credit to closing costs and keep more cash on hand.
Lower the price
Apply your credit directly to reduce the home’s purchase price.
How it works
How it works
Here's how to get thousands back on your new home.
Here's how to get thousands back on your new home.
Here's how to get thousands back on your new home.

STEP 1
STEP 1
Connect with Homa
Connect with Homa
Contact us before visiting a community to protect your eligibility for savings.

STEP 2
STEP 2
Tour Your New Home
Tour Your New Home
Explore homes with an experienced agent representing your interests.

STEP 3
STEP 3
Get Expert Guidance
Get Expert Guidance
our agent helps you navigate builder pricing, incentives, contracts, and inspections.

STEP 4
STEP 4
Close with More
Close with More
Close on your new home and receive up to 2% of the purchase price back.
Meet your team
Meet your team
The experts in your corner.
The experts in your corner.


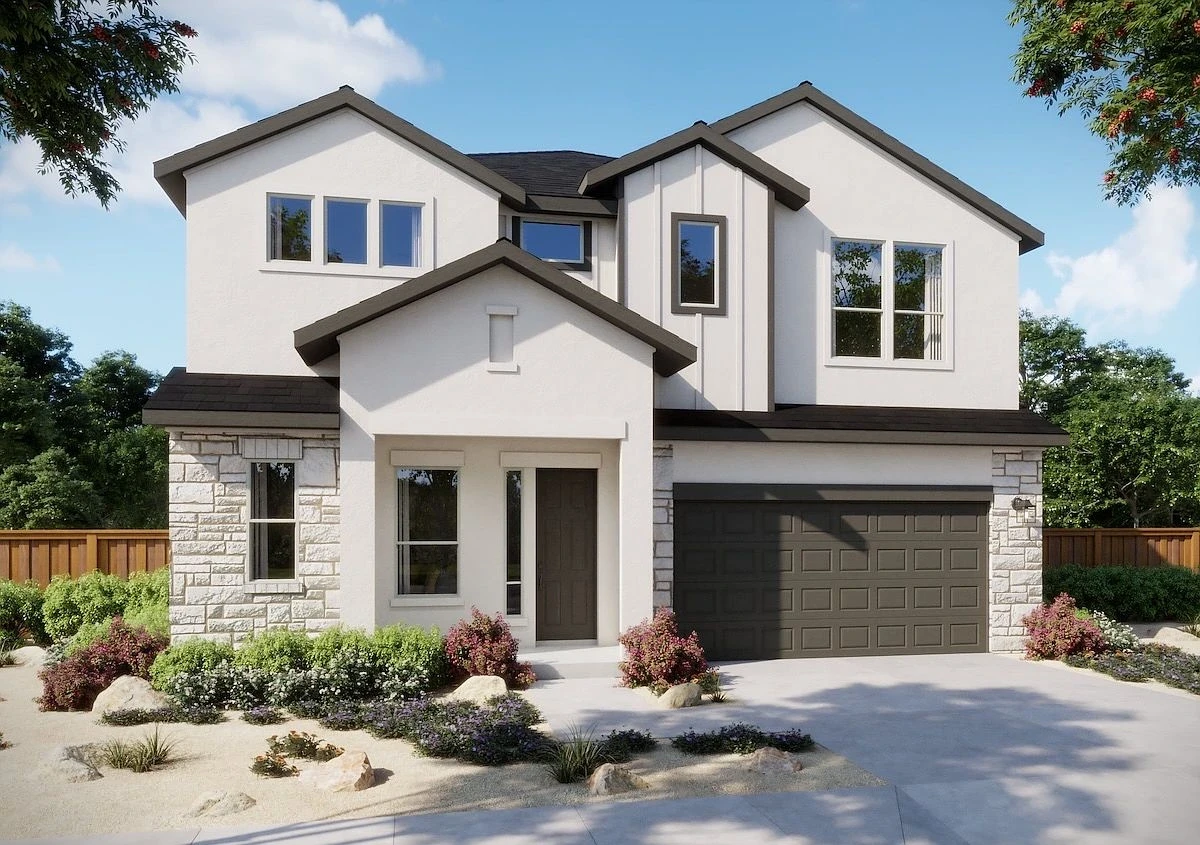
$940,000
2205 Sarabanda St, Round Rock, TX 78681
Homa Credit:
$18,800

$1,700,000
1426 Milan Ave, Coral Gables, FL 33134
Homa Credit:
$40,505

$817,000
1004 Duttons Meadow Lane, Mckinney, TX 75071
Homa Credit:
$16,340

$1,220,000
936 Windward Way, Weston, FL 33327
Homa Credit:
$36,600

$725,000
1123 Hounds Run, Safety Harbor, FL 34695
Homa Credit:
$19,755

$2,400,000
1610 Lost Cove Ln, Panama City Beach, Fl 32413
Homa Credit:
$58,005

$1,250,000
9334 Crestview Cir, Palm Beach Gardens, FL 33412
Homa Credit:
$18,750

$946,500
1929 Amalfi Court, St. Augustine, FL 32092
Homa Credit:
$16,491

$548,500
7237 Brinkley St, Navarre, Fl 32566
Homa Credit:
$11,717

$940,000
18295 Lake Bend Dr, Jupiter, FL 33458
Homa Credit:
$21,505
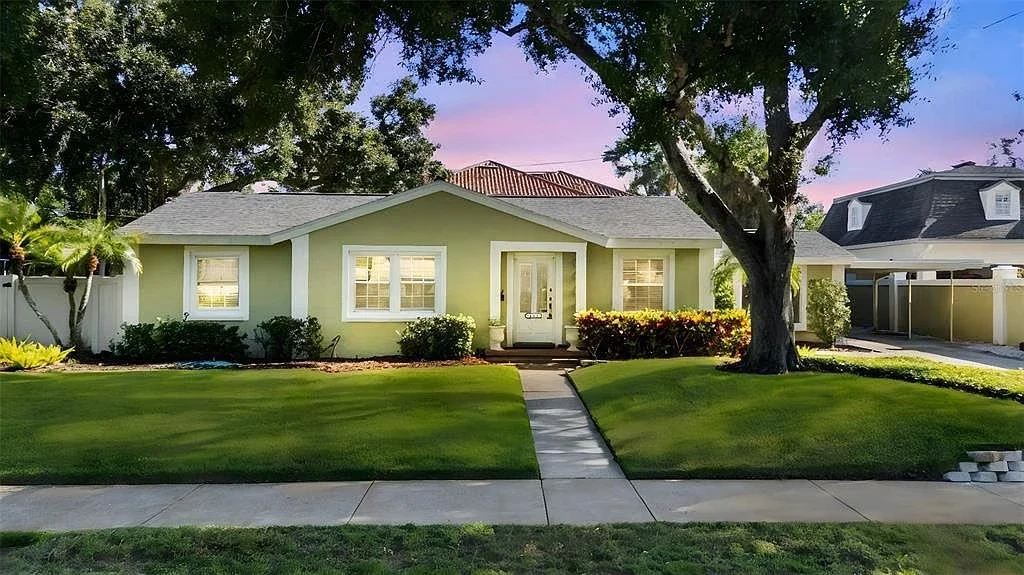
$899,000
4111 W Granada Street, Tampa, FL 33629
Homa Credit:
$26,970

$610,000
6024 NW Favian Ave, Port St. Lucie, Fl 34986
Homa Credit:
$11,350
recently closed with homa
The homes our buyers wanted. Negotiated and closed by our experts.
$940,000
2205 Sarabanda St, Round Rock, TX 78681
Homa Credit:
$18,800
$1,700,000
1426 Milan Ave, Coral Gables, FL 33134
Homa Credit:
$40,505
$817,000
1004 Duttons Meadow Lane, Mckinney, TX 75071
Homa Credit:
$16,340
$1,220,000
936 Windward Way, Weston, FL 33327
Homa Credit:
$36,600
$725,000
1123 Hounds Run, Safety Harbor, FL 34695
Homa Credit:
$19,755
$2,400,000
1610 Lost Cove Ln, Panama City Beach, Fl 32413
Homa Credit:
$58,005
$1,250,000
9334 Crestview Cir, Palm Beach Gardens, FL 33412
Homa Credit:
$18,750
$946,500
1929 Amalfi Court, St. Augustine, FL 32092
Homa Credit:
$16,491
$548,500
7237 Brinkley St, Navarre, Fl 32566
Homa Credit:
$11,717
$940,000
18295 Lake Bend Dr, Jupiter, FL 33458
Homa Credit:
$21,505
$899,000
4111 W Granada Street, Tampa, FL 33629
Homa Credit:
$26,970
$610,000
6024 NW Favian Ave, Port St. Lucie, Fl 34986
Homa Credit:
$11,350
recently closed with homa
Every home was found, negotiated, and closed with our experts.
$940,000
2205 Sarabanda St, Round Rock, TX 78681
Homa Credit:
$18,800
$1,700,000
1426 Milan Ave, Coral Gables, FL 33134
Homa Credit:
$40,505
$817,000
1004 Duttons Meadow Lane, Mckinney, TX 75071
Homa Credit:
$16,340
$1,220,000
936 Windward Way, Weston, FL 33327
Homa Credit:
$36,600
$725,000
1123 Hounds Run, Safety Harbor, FL 34695
Homa Credit:
$19,755
$2,400,000
1610 Lost Cove Ln, Panama City Beach, Fl 32413
Homa Credit:
$58,005
$1,250,000
9334 Crestview Cir, Palm Beach Gardens, FL 33412
Homa Credit:
$18,750
$946,500
1929 Amalfi Court, St. Augustine, FL 32092
Homa Credit:
$16,491
$548,500
7237 Brinkley St, Navarre, Fl 32566
Homa Credit:
$11,717
$940,000
18295 Lake Bend Dr, Jupiter, FL 33458
Homa Credit:
$21,505
$899,000
4111 W Granada Street, Tampa, FL 33629
Homa Credit:
$26,970
$610,000
6024 NW Favian Ave, Port St. Lucie, Fl 34986
Homa Credit:
$11,350
recently closed with homa
Every home was found, negotiated, and closed with our experts.
Buyer Stories
Buyer Stories
The Homa experience,
in their own words.
The Homa experience,
in their own words.

Frank
Repeat buyer · Doral, FL
I researched the company and liked what I saw. I like the transparency, the support, the coordinator. It was exactly what we were looking for.

DJ
First-time buyer · Tampa, FL
As a first-time buyer I was nervous, but it walks you through step-by-step. I saved $10,500 in commission — it’s all going back into the house.

John
First-time buyer · Temple Terrace, FL
It was exactly what I was looking for. Homa walked me through everything — and I walked away with money to make the house my own.
Frank
Repeat buyer · Doral, FL
I researched the company and liked what I saw. I like the transparency, the support, the coordinator. It was exactly what we were looking for.
DJ
First-time buyer · Tampa, FL
As a first-time buyer I was nervous, but it walks you through step-by-step. I saved $10,500 in commission — it’s all going back into the house.
John
First-time buyer · Temple Terrace, FL
It was exactly what I was looking for. Homa walked me through everything — and I walked away with money to make the house my own.
Frank
Repeat buyer · Doral, FL
I researched the company and liked what I saw. I like the transparency, the support, the coordinator. It was exactly what we were looking for.
DJ
First-time buyer · Tampa, FL
As a first-time buyer I was nervous, but it walks you through step-by-step. I saved $10,500 in commission — it’s all going back into the house.
John
First-time buyer · Temple Terrace, FL
It was exactly what I was looking for. Homa walked me through everything — and I walked away with money to make the house my own.
more reviews
5.0

Andrea Caruso
5.0
This was a perfect solution for my husband and I as buyers moving to Florida. We are a couple who likes the freedom of choosing houses we see online and going to look when our schedules allow. If you’re a buyer looking for homes in the states where Homa is active, it’s definitely the best realtor I would ever recommend. Lastly, the 2% closing credit was a big help in leaving us with extra cash to get our 2026 new build finished.

Bill Ruttencutter
5.0
Andrea was very helpful and professional during our process of looking for our new home. There was absolutely no pressure on us to hurry up and make a decision. Everything was explained to us with care and thought and our experience with Andrea was nothing short of outstanding.

Maryam Astero
5.0
We had an amazing experience working with Frank! He was super attentive, always responded to our messages immediately, and guided us through every step of buying our new home. Frank is a fantastic negotiator and fought hard to get us the best possible deal. He made what could have been a stressful process feel completely smooth and seamless.

Gary Peterson
5.0
Frank and the team at Homa was so professional and handled my purchase from beginning to end. The process was seamless and the level of knowledge and expertise was second to none! The end result was a substantial rebate back to me at closing that covered nearly all of my costs.

Monica M Dabaghi
5.0
I just closed on my new home in Texas with Homa and it was extremely pleasant. They helped me see 11 properties in 1 day, I had to move quickly and Homa got me an agent assigned to do my offer in less than a few hours when I was ready. They were extremely responsive, even got me a better deal than I thought I was going to get.

Funny Moniker
5.0
A little bit of learning curve with the process but the people and Homa could not have been more helpful. We loved the concept, method and experience. When we finally found our 'forever' home we were a assigned a realtor, Andrea who was outstanding.
more reviews
5.0
Andrea Caruso
5.0
This was a perfect solution for my husband and I as buyers moving to Florida. We are a couple who likes the freedom of choosing houses we see online and going to look when our schedules allow. If you’re a buyer looking for homes in the states where Homa is active, it’s definitely the best realtor I would ever recommend. Lastly, the 2% closing credit was a big help in leaving us with extra cash to get our 2026 new build finished.
Bill Ruttencutter
5.0
Andrea was very helpful and professional during our process of looking for our new home. There was absolutely no pressure on us to hurry up and make a decision. Everything was explained to us with care and thought and our experience with Andrea was nothing short of outstanding.
Maryam Astero
5.0
We had an amazing experience working with Frank! He was super attentive, always responded to our messages immediately, and guided us through every step of buying our new home. Frank is a fantastic negotiator and fought hard to get us the best possible deal. He made what could have been a stressful process feel completely smooth and seamless.
Gary Peterson
5.0
Frank and the team at Homa was so professional and handled my purchase from beginning to end. The process was seamless and the level of knowledge and expertise was second to none! The end result was a substantial rebate back to me at closing that covered nearly all of my costs.
Monica M Dabaghi
5.0
I just closed on my new home in Texas with Homa and it was extremely pleasant. They helped me see 11 properties in 1 day, I had to move quickly and Homa got me an agent assigned to do my offer in less than a few hours when I was ready. They were extremely responsive, even got me a better deal than I thought I was going to get.
Funny Moniker
5.0
A little bit of learning curve with the process but the people and Homa could not have been more helpful. We loved the concept, method and experience. When we finally found our 'forever' home we were a assigned a realtor, Andrea who was outstanding.
Frequently asked questions
Your Homa questions, answered.
Homa gives you on-demand tours, smart tools, unbiased guidance, and the right expert at every step, while giving you up to 2% back at closing. A traditional buyer’s agent charges up to 3% of the purchase price, often juggles multiple clients, and is expected to handle everything alone. Because their pay increases with the price you pay, their interests aren’t always aligned with yours. Homa’s experts are paid flat fees, and Homa keeps just 1%, so you get better support, better-aligned advice, and more value from your purchase.
In the vast majority of transactions, the seller pays a commission to the buyer’s broker. Homa acts as your buyer’s broker, claims that commission on your behalf, and rebates everything above our fee back to you. For example, if the seller offers a 3% commission on a $528,000 home, Homa keeps 1% ($5,280) and gives you the remaining 2% ($10,560) as a credit at closing.
You can, but in most cases, you will lose out on the entire buyer-agent commission. The agreement the listing agent has with the seller normally stipulates that the listing agent will pocket the full commission for both sides of the transaction if no buyer’s broker is involved. You could end up doing all the work yourself while the listing agent keeps the savings. With Homa, we claim the buyer’s agent commission on your behalf and give most of it back to you at closing.
Your Homa credit, up to 2% of the price, is applied at closing. You choose how to use it: cover closing costs, lower the price, or buy down your mortgage rate for a lower monthly payment, within your lender's limits. If you're paying cash, the credit reduces the total amount you bring to closing.
Frequently asked questions
Your Homa questions, answered.
Homa gives you on-demand tours, smart tools, unbiased guidance, and the right expert at every step, while giving you up to 2% back at closing. A traditional buyer’s agent charges up to 3% of the purchase price, often juggles multiple clients, and is expected to handle everything alone. Because their pay increases with the price you pay, their interests aren’t always aligned with yours. Homa’s experts are paid flat fees, and Homa keeps just 1%, so you get better support, better-aligned advice, and more value from your purchase.
In the vast majority of transactions, the seller pays a commission to the buyer’s broker. Homa acts as your buyer’s broker, claims that commission on your behalf, and rebates everything above our fee back to you. For example, if the seller offers a 3% commission on a $528,000 home, Homa keeps 1% ($5,280) and gives you the remaining 2% ($10,560) as a credit at closing.
You can, but in most cases, you will lose out on the entire buyer-agent commission. The agreement the listing agent has with the seller normally stipulates that the listing agent will pocket the full commission for both sides of the transaction if no buyer’s broker is involved. You could end up doing all the work yourself while the listing agent keeps the savings. With Homa, we claim the buyer’s agent commission on your behalf and give most of it back to you at closing.
Your Homa credit, up to 2% of the price, is applied at closing. You choose how to use it: cover closing costs, lower the price, or buy down your mortgage rate for a lower monthly payment, within your lender's limits. If you're paying cash, the credit reduces the total amount you bring to closing.
Frequently asked questions
Your Homa questions, answered.
Homa gives you on-demand tours, smart tools, unbiased guidance, and the right expert at every step, while giving you up to 2% back at closing. A traditional buyer’s agent charges up to 3% of the purchase price, often juggles multiple clients, and is expected to handle everything alone. Because their pay increases with the price you pay, their interests aren’t always aligned with yours. Homa’s experts are paid flat fees, and Homa keeps just 1%, so you get better support, better-aligned advice, and more value from your purchase.
In the vast majority of transactions, the seller pays a commission to the buyer’s broker. Homa acts as your buyer’s broker, claims that commission on your behalf, and rebates everything above our fee back to you. For example, if the seller offers a 3% commission on a $528,000 home, Homa keeps 1% ($5,280) and gives you the remaining 2% ($10,560) as a credit at closing.
You can, but in most cases, you will lose out on the entire buyer-agent commission. The agreement the listing agent has with the seller normally stipulates that the listing agent will pocket the full commission for both sides of the transaction if no buyer’s broker is involved. You could end up doing all the work yourself while the listing agent keeps the savings. With Homa, we claim the buyer’s agent commission on your behalf and give most of it back to you at closing.
Your Homa credit, up to 2% of the price, is applied at closing. You choose how to use it: cover closing costs, lower the price, or buy down your mortgage rate for a lower monthly payment, within your lender's limits. If you're paying cash, the credit reduces the total amount you bring to closing.
before you visit
Contact us before visiting your {{builder}} home in {{city}}
Most builders require you to register your buyer's agent before your first visit. Connect with Homa first to protect your eligibility for up to 2% back at closing.
before you visit
Contact us before visiting your {{builder}} home in {{city}}
Most builders require you to register your buyer's agent before your first visit. Connect with Homa first to protect your eligibility for up to 2% back at closing.
before you visit
Contact us before visiting your {{builder}} home in {{city}}
Most builders require you to register your buyer's agent before your first visit. Connect with Homa first to protect your eligibility for up to 2% back at closing.